Sales Margin Calculator
Sales Margin Calculator
Work out gross profit, sales margin % and markup % — or find the price that hits your target margin.
The sales margin formula is: sales margin % = (revenue − cost) ÷ revenue × 100. Enter your selling price and the cost of the goods into the calculator above and it works out your gross profit, your sales margin, and your markup — or switch to target-margin mode and it tells you the price you need to charge to hit the margin you want.
What is the sales margin formula?
The sales margin formula measures how much of each sale you keep as profit after paying for the goods themselves. Take the revenue from a sale, subtract the cost of the goods sold, and divide the result by the revenue. Multiply by 100 to turn it into a percentage. In symbols: sales margin % = (revenue − cost of goods sold) ÷ revenue × 100.
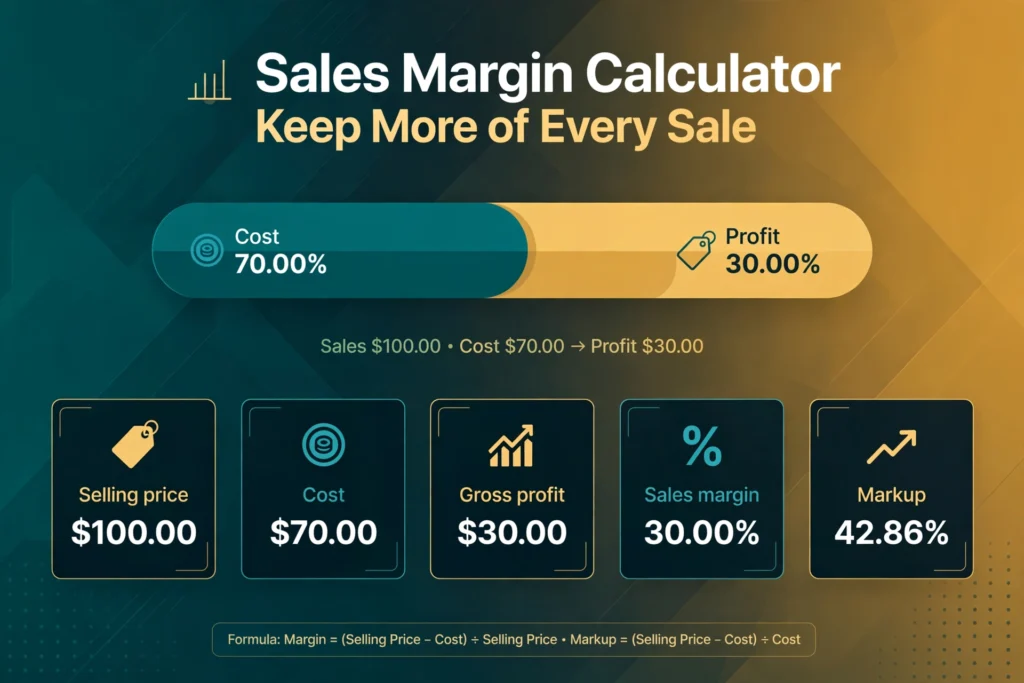
A $100 sale with a $70 cost gives a gross profit of $30. Divide that $30 by the $100 selling price and you get 0.30, or a 30% sales margin. That means 30 cents of every dollar collected stays as gross profit, and the other 70 cents covers the cost of the goods.
Sales margin and gross profit margin are the same calculation. The two names describe different settings: “sales margin” usually means the margin on one sale or one product, while “gross profit margin” usually means the same figure for a whole business over a period. The formula does not change, only the scale of the numbers fed into it.
One point matters from the start: this formula counts direct costs only. The cost of the goods sold covers what you paid for the stock, the materials, and the labour that went directly into making or buying the item. Rent, marketing, software, and other running costs are not in this formula. That is why the result is called a gross margin — it shows the profit before those other costs are paid.
How do you calculate sales margin step by step?
Calculating a sales margin takes three steps, and each one uses numbers you already have from a single sale.
First, find the gross profit. Subtract the cost of the goods from the selling price. A product that sells for $100 and costs $70 leaves $30 of gross profit. If you sell more than one unit, use the totals instead: total revenue minus total cost of the goods sold gives the same figure for the whole batch.
Second, divide the gross profit by the revenue. Using the same sale, $30 divided by $100 gives 0.30. This step is where most mistakes happen, because the divisor is the selling price, not the cost. Dividing by the cost gives a different number — the markup — and the two are easy to mix up.
Third, multiply by 100 to get a percentage. 0.30 times 100 is 30%, so the sales margin is 30%. The percentage is what makes the figure useful: a 30% margin means the same thing whether the sale was $10 or $10,000, so you can compare products, suppliers, and months on equal terms.
The calculator above follows exactly these steps. Enter the selling price and the cost, and it shows the gross profit, the margin, and the markup together, so you can see all three numbers from one sale without working them out by hand.
What is the difference between sales margin and markup?
Sales margin and markup describe the same profit with different divisors. Margin divides the profit by the selling price. Markup divides the same profit by the cost. On a $100 sale with a $70 cost, the profit is $30 either way — but the margin is $30 ÷ $100 = 30%, while the markup is $30 ÷ $70 = 42.86%.
Markup is always the higher percentage on the same sale, because the cost is always smaller than the selling price. That gap grows as the margin rises: a 50% margin needs a 100% markup, and a 70% margin needs a 233.33% markup. The two figures only meet at zero, where both are 0%.
The practical difference is what each one is for. Margin answers the question “how much of this sale do I keep?” and is the right figure for judging whether a product is worth selling. Markup answers the question “how much do I add on top of my cost?” and is the figure most often used when setting a price from a cost. Mixing them up is the most common pricing mistake there is: aiming for a 30% margin but adding a 30% markup gives a price of $91 on a $70 cost, and a margin of only 23.08%.
To convert between them, use these two formulas. Margin = markup ÷ (1 + markup). Markup = margin ÷ (1 − margin). Both work with the percentages written as decimals, so 30% is 0.30. A 42.86% markup converts back to 0.4286 ÷ 1.4286 = 0.30, a 30% margin — the same sale, seen from the other side.
How do you find the selling price for a target margin?
When you know the margin you want, work backwards from the cost. The formula is: selling price = cost ÷ (1 − target margin). Write the target margin as a decimal, so 40% becomes 0.40. A product that costs $80 with a target margin of 40% needs a price of $80 ÷ (1 − 0.40) = $80 ÷ 0.60 = $133.33.
The tempting shortcut is to add the margin to the cost instead — $80 plus 40% is $112. That gives a profit of $32 on a $112 price, which is a margin of only 28.57%. The shortcut fails because it divides the profit by the wrong number. The correct formula divides by one minus the margin, which is what makes the profit come out as the right share of the final price.
The target-margin mode of the calculator above does this calculation for you. Enter the cost and the target margin, and it shows the selling price you need, the profit at that price, and the markup that price implies. For a $100 cost, the prices run from $111.11 at a 10% target margin up to $200.00 at a 50% target margin — the full table is below, in the quick-reference section.
Two limits apply. A target margin of 100% is impossible with any positive cost, because it would mean the whole price is profit and nothing is left to cover the cost. A target margin of 0% just repeats the cost as the price, with no profit at all. The calculator refuses both and asks for a target between 0% and 100%.
What is a good sales margin?
There is no single good sales margin, because the right figure depends on the industry and on how much it costs to run the business. A grocery shop can thrive on a thin margin because it sells a large volume every day. A service business with few direct costs can carry a much higher margin on each job. The margin has to be large enough to cover the running costs that sit below it — rent, wages, marketing, fees — and still leave a profit.
A rule of thumb often quoted from the Corporate Finance Institute puts 5% as low, 10% as average, and 20% as high for profit margins. Treat that as a rough guide, not a target: it describes net profit margins, which include every cost, while the sales margin on this page covers direct costs only. A sales margin of 30% can still leave a thin net margin once the running costs are paid.
The better way to judge your margin is to compare it with your own history and with your own costs. Work out the margin your business needs by adding up the running costs for a month and dividing by the month’s revenue — that percentage is the margin below which the business loses money. A product margin above that line contributes to profit; a product margin below it does not, however large the sales look.
Discounts deserve a warning here, because they cut margins faster than most people expect. A 10% discount on a product with a 30% margin does not cut the margin to 20%. On a $100 sale with a $70 cost, a 10% discount drops the price to $90 while the cost stays at $70, so the profit falls from $30 to $20 and the margin falls from 30% to 22.22%. The discount comes straight out of the profit, never out of the cost. The Discount Calculator shows how a discount changes the price you actually collect.
What costs count in the sales margin formula?
The cost in the sales margin formula is the cost of goods sold: the direct cost of getting the item ready to sell. For a retailer, that is the wholesale price paid for the stock, plus freight and any import charges on it. For a maker, it is the materials and the labour that went directly into producing the item. For a service business, it is the direct cost of delivering the job — materials used on the job and any subcontractor charges.
Running costs stay out of this formula. Rent, utilities, marketing, insurance, software subscriptions, and office wages are operating expenses, not part of the cost of goods sold. They are real costs, and they decide whether the business as a whole makes money, but they belong in the operating margin and the net margin, not in the sales margin.
Sales commissions sit in a grey area, and the honest approach is to decide once and stay consistent. Some businesses count commission as a direct cost of the sale; others treat it as an operating expense. Either choice is defensible, but switching between them makes month-to-month comparisons meaningless. If your sales team earns commission on each deal, the Commission Pay Calculator works out what that commission costs you per sale.
Taxes also stay out. Sales tax or VAT collected from the customer belongs to the tax authority, not to you, so work out margins on tax-exclusive prices. Mixing tax-inclusive prices into the formula inflates the revenue and makes the margin look better than it is.
What is the difference between sales margin and maintenance margin?
Sales margin and maintenance margin share a word and nothing else. Sales margin is a pricing figure: the share of a selling price kept as profit after paying for the goods. Maintenance margin is a stock-trading term: the minimum equity a trader must keep in a margin account — an account where the broker lends money to buy shares.
The two are confused because both appear in searches for “margin calculator”. A maintenance margin calculator asks for the value of the shares held, the amount borrowed, and the broker’s required percentage, then works out whether the account is at risk of a margin call. Under US Federal Reserve Regulation T, the minimum maintenance margin is 25% of the total value of the securities in the account, though most brokers require more. If the equity in the account falls below that level, the broker can demand more money or sell shares to restore it.
This page is about the sales kind of margin, not the trading kind. The calculator here takes a selling price and a cost, not a share price and a loan. If you arrived looking for a trading margin, the figures on this page will not help — and if you arrived looking for a sales margin, the 25% Regulation T figure has nothing to do with your prices.
What mistakes do people make with sales margin?
The first mistake is using markup when the target is a margin. Aiming for a 30% margin and adding a 30% markup is the classic version, and it leaves the margin at 23.08% instead of 30%. The fix is to use the target-price formula — cost divided by one minus the margin — or to use the calculator’s target-margin mode.
The second mistake is forgetting a cost. The most common one is freight: the stock cost $70, but delivery added $8, so the real cost is $78 and the margin on a $100 sale is 22%, not 30%. Packaging, payment-processing fees, and returns work the same way. Any cost that only exists because the sale happened belongs in the cost figure.
The third mistake is treating the sales margin as the final profit. A 30% sales margin does not mean 30% of revenue ends up in your pocket. Rent, wages, marketing, and tax still have to be paid from that 30%. The margin is the pool those costs are paid from, not what is left after them. Judging a business by its sales margin alone is like judging a household by its salary before the bills.
The fourth mistake is setting one margin for every product. A fast-selling product with a 20% margin can earn more in a month than a slow product with a 50% margin, because the fast one turns over many times. Margin and volume have to be judged together, and dropping a low-margin product that brings customers through the door can cost more than it saves.
The fifth mistake is pricing from the competition instead of from the cost. Matching a rival’s price feels safe, but if your costs are higher than theirs, the same price gives you a thinner margin — or a negative one. The price has to cover your cost first; the competition’s price is a check on whether customers will pay it, not a substitute for the maths. The ROI Calculator takes the same kind of thinking further, by comparing what you put in against what you get back over time.
How do you use this sales margin calculator?
Choose what you want to find. “My margin on a sale” works out the margin from a selling price and a cost. “Price for a target margin” works out the selling price from a cost and the margin you want. The two modes share the same formulas, run in opposite directions.
In margin mode, enter the selling price — the amount the customer actually pays — and the cost of the goods. The calculator shows the gross profit in dollars, the sales margin as a percentage of the selling price, and the markup as a percentage of the cost. If the cost is higher than the price, it shows a negative margin and says plainly that the sale loses money.
In target-margin mode, enter the cost of the goods and the margin you want, as a percentage. The calculator shows the selling price you need to charge, the profit at that price, and the markup that price implies. The markup will always be higher than the margin — on a 40% target margin with an $80 cost, the price is $133.33 and the markup is 66.67%.
Enter prices and costs without tax, and keep the currency consistent: if the cost is in dollars, the price must be in dollars too. The results update as you type, so you can test a higher price or a lower cost and watch the margin move at once.
What does the sales margin formula look like on a real sale?
Take a product that costs $70 and sells for $100. The gross profit is $100 − $70 = $30.00. The sales margin is $30.00 ÷ $100 × 100 = 30.00%. The markup is $30.00 ÷ $70 × 100 = 42.86%. One sale, one profit of $30.00, and two percentages that describe it from opposite sides.
Now suppose the seller wants a 40% margin on a different product that costs $80. Adding 40% to the cost would give $112 — but that price gives a margin of only 28.57%. The correct price is $80 ÷ (1 − 0.40) = $133.33. At that price the profit is $53.33, the margin is $53.33 ÷ $133.33 × 100 = 40.00%, and the markup is $53.33 ÷ $80 × 100 = 66.67%.
A second sale shows how the figures move: a $250 sale with a $180 cost leaves $70.00 of profit, a margin of 28.00%, and a markup of 38.89%. The profit is larger than in the first sale, but the margin is lower, because the cost takes a bigger share of the price. Comparing margins, not profits, is what shows which sale is actually stronger.
And a sale can go wrong. A $90 price on a $120 cost loses $30.00, giving a margin of −33.33% and a markup of −25.00%. The negative margin is the warning sign: the price does not cover the cost, and every sale at that price makes the loss bigger. Raising the price to $120 would only break even; the price has to go above $120 before the sale makes anything.
The quick-reference tables below are computed from the same formulas, so any row can be checked by hand. The first table holds the cost at $60 and raises the price; the second holds the cost at $100 and raises the target margin. Both show the same pattern: as the price rises, the margin climbs towards 100% but never reaches it, while the markup climbs without any limit.
| Selling price | Gross profit | Sales margin | Markup |
|---|---|---|---|
| $80.00 | $20.00 | 25.00% | 33.33% |
| $100.00 | $40.00 | 40.00% | 66.67% |
| $120.00 | $60.00 | 50.00% | 100.00% |
| $150.00 | $90.00 | 60.00% | 150.00% |
| $200.00 | $140.00 | 70.00% | 233.33% |
| Target margin | Selling price needed | Gross profit at that price |
|---|---|---|
| 10% | $111.11 | $11.11 |
| 20% | $125.00 | $25.00 |
| 30% | $142.86 | $42.86 |
| 40% | $166.67 | $66.67 |
| 50% | $200.00 | $100.00 |
This page gives general information about sales margins and how the numbers work. It is not financial advice, and it does not take your full situation into account. If you need pricing or business advice for your own circumstances, speak to a qualified professional. Figures on this page are worked from the numbers you enter; check them against your own costs before setting a price. Percentages are handy for comparing sales — the Percentage Calculator can work out a percentage of any number when you need a quick figure outside this tool.
What is the sales margin formula?
Sales margin % = (revenue − cost of goods sold) ÷ revenue × 100. For a $100 sale with a $70 cost, the gross profit is $30 and the sales margin is $30 ÷ $100 × 100 = 30%.
What is the difference between sales margin and markup?
Both use the same profit, but margin divides it by the selling price and markup divides it by the cost. On a $100 sale with a $70 cost, the margin is 30% and the markup is 42.86%. Markup is always the higher percentage on the same sale.
How do I calculate the selling price for a target margin?
Use selling price = cost ÷ (1 − target margin), with the margin as a decimal. For a cost of $80 and a 40% target margin, the price is $80 ÷ 0.60 = $133.33. Adding the margin to the cost instead gives the wrong price.
What is a good sales margin?
It depends on the industry and on your running costs — there is no single good figure. A rough rule of thumb puts 5% as low, 10% as average, and 20% as high for profit margins, but your margin must be large enough to cover rent, wages, marketing, and tax and still leave a profit.
Is sales margin the same as gross profit margin?
Yes, the formula is the same: (revenue − cost of goods sold) ÷ revenue × 100. “Sales margin” usually means the margin on one sale or product, while “gross profit margin” usually means the same figure for a whole business over a period.
What is maintenance margin, and is it the same as sales margin?
No. Maintenance margin is a stock-trading term: the minimum equity a trader must keep in a margin account, with a minimum of 25% of the securities’ value under US Federal Reserve Regulation T. Sales margin is the share of a selling price kept as profit after paying for the goods. The two share a word and nothing else.